What Is Spinhank Charge on Credit Card?

A Spinhank charge on your credit card is an unfamiliar billing description that you should verify promptly. Consumer complaint websites include reports of card transactions labeled Spinhank or Spinhank.com, but those reports do not establish a verified legal business identity or prove that every transaction using the name is fraudulent. We could not confirm a reliable official merchant statement explaining exactly what service the descriptor represents.
If you do not recognize the amount, contact your card issuer using the number on the back of your card. Ask for the full merchant details and report any charge you did not authorize. Do not enter payment information into an unverified website that claims it can cancel the charge.
What Is Spinhank Charge on a Credit Card?
Spinhank appears in several consumer-submitted complaints about unexpected card billing. Those reports suggest some cardholders encountered the name while reviewing online transactions. However, public complaints do not substitute for an invoice, merchant registration, or confirmation from a payment processor.
For that reason, the most accurate answer is limited: Spinhank is a reported card descriptor whose underlying merchant identity is not reliably established by the primary public evidence reviewed. You should treat the charge as unidentified until your issuer confirms who received payment.
What do public complaints say?
A consumer complaint directory lists reports involving the spelling Spinhank.com, including allegations of unexpected payments and difficulty reaching support. The claims come from individual submitters and have not necessarily been independently verified.
Do not assume a specific amount reported by someone else is the normal price of a Spinhank product. Complaint pages may include mistaken or incomplete details. Your bank’s transaction record is a stronger source for understanding your own case.
Is Spinhank a confirmed scam?
We cannot conclude that every Spinhank transaction is fraudulent from the name or consumer reports alone. At the same time, the lack of transparent primary merchant information is a reason to investigate rather than automatically trusting the charge.
Fraud is determined from whether the payment was authorized and the surrounding facts. If you never bought anything from the merchant, report the transaction promptly. If it corresponds to an authorized purchase, ask your issuer or the merchant for an explanation of the billing name.
How to identify the Spinhank payment
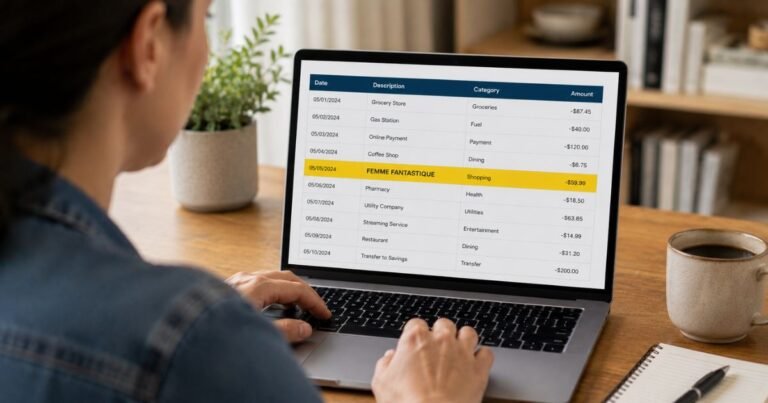
- Open the transaction in your card issuer’s official app or website.
- Save the full descriptor, date, posted amount, and any city or telephone information.
- Search your own purchase confirmations for matching amounts and dates.
- Ask other authorized card users if they recognize the transaction.
- Request the full merchant details from the card issuer.
- Report a payment you did not authorize and follow the issuer’s fraud instructions.
A statement may show a shortened website name or additional letters after the merchant. Keep the entire text as displayed when you contact the issuer. Do not publish the statement publicly or share sensitive account identifiers in comment sections.
What if the charge includes a website address?
A domain name can help identify where a payment may have originated, but the address alone does not prove the person behind the website or confirm the service purchased. Verify any site before entering personal data or seeking cancellation.
If your banking app shows Spinhank.com or a similar domain, ask the bank whether that is its recorded merchant address. Do not trust a website solely because its name matches the descriptor; fraudulent and lookalike domains can create confusion.
Could it be a subscription?
Some consumer reports involve charges that appeared to recur. But we did not find a trustworthy official subscription agreement establishing a standard Spinhank price, renewal period, or cancellation policy. Therefore, no monthly membership should be assumed from the descriptor alone.
Check whether your card shows several posted payments to the same merchant. Ask the issuer whether the transactions were marked as recurring. If an authorized subscription can be identified, request cancellation through the verified provider. If it was not authorized, report it immediately.
What if Spinhank charged a small amount?
A small, unfamiliar amount is still worth investigating. The size of a transaction does not make it safe. Banks and regulators encourage consumers to review account activity and report charges they did not authorize.
Do not wait for a bigger payment before contacting your issuer. If the first entry is pending, the bank can tell you what controls or security steps are appropriate while it determines whether the charge will settle.
What if the card was used online?
Online merchants can process transactions without physically seeing a payment card. A statement location may therefore indicate a merchant’s registered address rather than where the customer made the purchase.
Check recent sites on which you knowingly entered your card details, but do not assume one site caused the charge without supporting evidence. Preserve receipts and confirmation emails that may help your issuer determine what happened.
How to stop future unauthorized charges
Call the issuer’s fraud department or use the security controls in its official app. Ask about locking the card, replacing the number, disputing the transaction, and reviewing additional activity. Follow the bank’s advice on securing connected digital wallets and saved payment methods.
For a genuine subscription you authorized, cancellation with the provider may still be necessary. A new card number does not always terminate every recurring payment relationship. See our guide to blocking unwanted credit card charges.
Can you receive a refund?
When the merchant is identified and the charge relates to an order you recognize, a refund may depend on the merchant’s terms and the reason you are seeking repayment. For an unauthorized charge, contact the card issuer promptly and ask about investigation and applicable protections.
A temporary credit received during a dispute is not necessarily a permanent refund. The issuer can explain what evidence it needs, how the investigation works, and when you will receive a final decision.
How to file a billing dispute
Tell the issuer the exact date, amount, and description, and explain why the charge is wrong or unauthorized. Save the case number and copies of any supporting documents. Do not guess which business owns the charge when you cannot verify it.
For certain U.S. credit card billing errors, the CFPB advises that a written notice be sent within 60 calendar days after the statement showing the error was sent. Use the address specified for billing inquiries and continue paying undisputed amounts on time.
What if the bank identifies a legitimate retailer?
Sometimes the issuer has more complete merchant information than the short statement view. A verified name, location, and transaction reference may explain a purchase whose descriptor looked mysterious.
Compare the result against a real receipt or service contract. If it still does not match, ask the issuer to investigate. You do not have to accept a charge merely because the company itself is legitimate.
How to avoid unsafe support offers
Beware of people who offer to reverse Spinhank charges in exchange for a processing fee or request your card number and one-time verification code. A legitimate dispute begins with your card issuer, not with someone approaching you through a public complaint thread.
Search only through recognized official channels and keep a record of who you contacted. Read our guide to identifying unknown charges for additional practical steps.
What we could not verify
We could not independently verify a legal entity, official transaction descriptor guide, standardized service description, fixed price, or current customer-support details for Spinhank. Any article that assigns a specific product or refund policy without that evidence risks misleading readers.
If you can obtain a fuller statement description from your bank, it may resolve the identity. Until then, the safest classification is an unexplained merchant charge, not a proven scam or proven legitimate subscription.
Helpful sources
- CFPB: Fixing Credit Card Billing Mistakes
- CFPB: Dispute Rights and Deadlines
- Consumer Reports About Spinhank (Unverified Allegations)
FAQs About Spinhank Credit Card Charges
Q. What company owns Spinhank?
A. We did not find a reliable primary source establishing the legal merchant identity behind the reported card descriptor.
Q. Is every Spinhank charge fraudulent?
A. No such conclusion is supported. Confirm whether your own payment was authorized and ask the issuer to investigate.
Q. Can I cancel Spinhank online?
A. We could not verify a current official cancellation procedure. Use the issuer to identify the merchant before sharing card information with a website.
Q. Should I dispute a charge I never authorized?
A. Yes. Report an unauthorized credit card charge promptly using your card issuer’s official channels.
Conclusion
A Spinhank charge on your credit card is not reliably identifiable from public merchant documentation. Review your receipts, ask your issuer for full merchant details, and report any unauthorized transaction without delay.
Disclaimer: This article provides general U.S. consumer education, not personalized legal or financial advice. Consumer complaints referenced here are unverified reports and do not establish wrongdoing by a specific company.