What is Minimum Interest Charge on Credit Card?

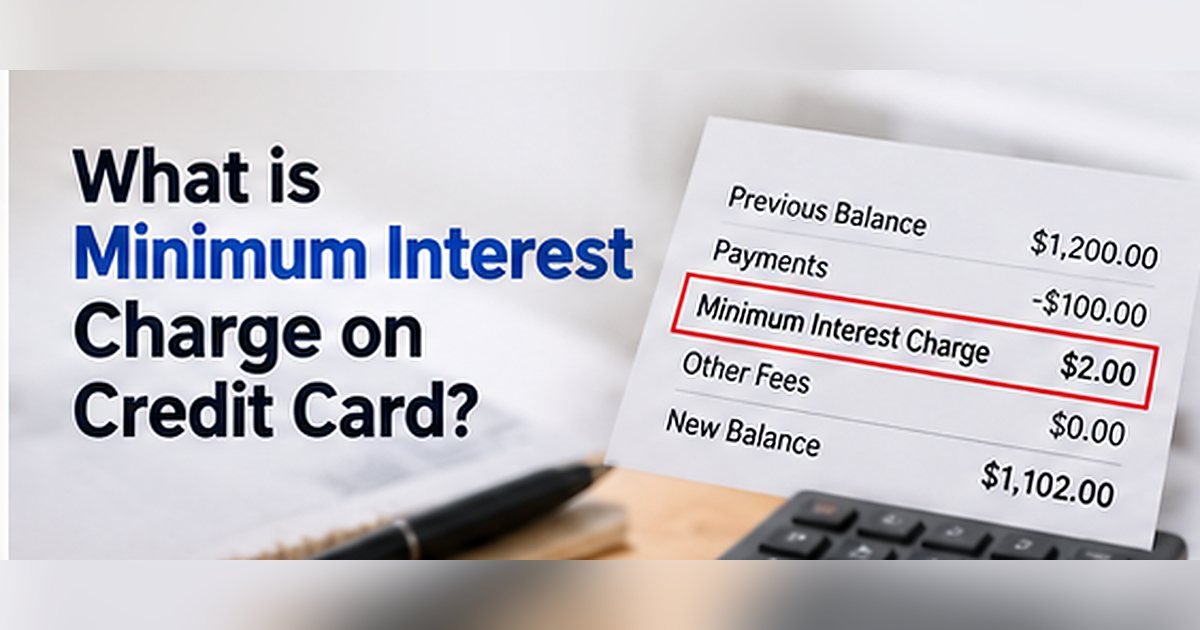
A minimum interest charge on credit card statements may appear even when you expected to owe only a few cents. It is usually a disclosed minimum amount of interest, not an unexplained merchant purchase.
If the entry does not make sense at first glance, you do not need to guess. Verify the amount, the billing history, and the rules that apply to your account before taking action.
What Is a Minimum Interest Charge on Credit Card?
Some card agreements set a floor on the interest charged in a billing cycle when an interest charge is otherwise due; see our related minimum charge guide for the difference from minimum payments. For example, if the calculated interest would be smaller than the disclosed minimum, the issuer may assess the minimum amount instead. A minimum interest charge is different from your minimum monthly payment.
The CFPB identifies minimum finance charges as a specific credit card pricing term, and federal disclosure rules address how issuers describe them. Not every card has one, and the amount varies by agreement. You should read your card’s pricing table before assuming a particular dollar amount applies.
A simple minimum interest example
Imagine that your card agreement has a $1 minimum interest charge in a cycle where interest is due. If the actual interest calculation comes to 42 cents, the issuer may charge $1 under that disclosed term. The extra 58 cents is not a separate store purchase.
If the regular calculated interest is higher than the stated minimum, the ordinary calculation usually applies instead. This example is illustrative; it is not a claim about your card’s terms. Some issuers have no such provision or apply it only to particular balances.
Why it can happen on a nearly paid-off balance
Suppose you carried a purchase balance during part of the previous cycle and then paid most of it. A small amount of interest can still accrue before the bank credits your payment. If that interest is below the minimum written in your contract, the floor may become visible.
Residual interest can also appear after you believe you paid the account in full. Ask whether the charge is trailing interest or a minimum finance charge. The labels describe related but different features of the calculation.
Is it the same as a late-payment fee?
No. Late fees generally relate to missing a required payment deadline, while minimum interest charges relate to how the interest amount is determined. A separate annual fee, transaction fee, or cash-advance fee has its own terms.
Check the statement’s fee summary and interest-charge section rather than relying on a single line description. The distinction matters because the solution may be paying off an interest-bearing balance, not disputing a merchant or asking for late-fee removal.
When you may avoid this charge
If your purchase grace period is in effect and you pay the required statement balance in full by the due date, you can often avoid purchase interest. When no interest is due, a minimum interest provision generally should not create interest by itself. Cash advances and special balance categories may follow different rules.
If your card has lost its purchase grace period, it can take more than one statement cycle to stop interest completely. Confirm with the issuer what balance must be paid and when the grace period can be restored.
Where to find the exact policy
Review the Schumer box or pricing table supplied with your card agreement. Look for wording such as Minimum Interest Charge, Minimum Finance Charge, or Minimum Charge. Some issuers disclose the condition and amount under that heading.
You can request the applicable agreement from the issuer or review agreements through the CFPB database. Focus on the version and terms that apply to your account, not a generic example from another bank. If a charge conflicts with your agreement, ask the issuer to explain the calculation.
How to query or dispute a mistake
Ask customer service to identify the affected balance category, the interest amount before the minimum, and the disclosed charge floor. Keep notes about the explanation. If the bank applied a provision that does not appear in your agreement, request a correction and consider its formal billing-error process.
Do not ignore a statement while the question is being reviewed. Continue paying at least the undisputed required amount on time. Preserve any available statutory dispute rights with timely written notice if the issue qualifies.
Locate the rate and balance on your statement
Find the section usually labeled interest charge calculation. It may list purchases, balance transfers, and cash advances separately, each with its own annual percentage rate and balance subject to interest. Do not apply one purchase APR to every balance on the account.
Also find the billing-cycle closing date, payment due date, statement balance, current balance, and any promotional terms. These numbers serve different purposes. The statement balance is the amount billed at closing, while the current balance may change after the cycle ends.
Understand the grace period
Many cards provide a purchase grace period when you meet their conditions, commonly paying the statement balance in full by the due date. When a grace period applies, new purchases can avoid interest. Cash advances often have no comparable grace period, and their rates or fees may be higher.
If you have carried a balance, you may continue to owe residual or trailing interest after making a payment. Interest can accrue between the statement closing date and the day your payment is credited. Ask your issuer for the precise payoff amount if you are trying to bring the account to zero.
Know why daily balances matter
Issuers commonly use an average daily balance or daily balance method. Payments reduce the balance used in the interest calculation once they are credited, while new transactions can increase it. This means the timing of a payment can matter even when two people pay the same total by the end of a month.
Your card agreement explains its actual calculation method and whether interest compounds. Some simplified examples use APR divided by 365, but the card may disclose a different divisor or special rules. Treat any online estimate as an approximation until it matches your contract.
Separate interest from other charges
A statement may show interest charges near annual fees, late fees, balance-transfer fees, or cash-advance fees. They do not all arise for the same reason. A low balance is not a guarantee of zero charges if your agreement includes a minimum interest amount and interest would otherwise be due.
Read the statement line descriptions carefully. A payment that looks too small to affect your interest may still lower future interest by reducing principal. Likewise, making only the required minimum generally costs more over time than paying an additional amount toward the balance.
Protect yourself from calculation mistakes
Check whether you copied the APR as a percentage or a decimal. For example, a 24% APR is 0.24 in a formula, not 24. Make sure the number of days corresponds to the actual billing cycle and that payments occur on the dates used in your calculation.
Compare estimated interest with the next statement and investigate meaningful differences. New purchases, cash advances, compounding, fees, and varying daily balances can all change the result. Contact the issuer for the detailed method rather than treating a simple calculator as the final bill.
Example of the effect of paying earlier
Imagine a $1,000 interest-bearing purchase balance and a 24% APR for a simple illustration. At an assumed 365-day divisor, the daily rate is about 0.0658%, or roughly 66 cents per day on an unchanged $1,000 balance. Actual figures vary with balance changes and your issuer’s calculation.
A $200 payment made earlier in the cycle can reduce later daily interest compared with waiting to make that same payment. This does not mean that every card uses identical compounding or that your final charge can be computed from one average. Your account agreement governs.
How to discuss a surprise amount with the bank
Ask the issuer which balance category generated the charge, which APR applied, and the daily-balance period used. If there is a minimum interest provision, request the specific disclosure that explains it. Keep notes about the representative’s explanation and check it against the statement.
When you think a posted interest amount is a true billing error, use the issuer’s billing-error process rather than assuming the amount will vanish. Preserve your rights with timely written notice when applicable. Continue paying the undisputed portion of the account as required.
Official sources and further reading
CFPB: Minimum finance charge definition; CFPB: Credit card agreements; CFPB: How interest is calculated. Review the original sources for current procedures, and use the card issuer’s own agreement for account-specific terms.
FAQs On Minimum Interest
Q: Is a minimum interest charge a penalty?
A: Generally, no. It is a contractual minimum applied when interest would otherwise be due, not a late-payment penalty.
Q: Can a card issuer charge a minimum of $1?
A: Some agreements use a minimum amount, but the actual number and conditions vary. Check your card’s disclosures.
Q: Why did it appear after I made a payment?
A: Residual interest may have accrued before payment posting, and a disclosed minimum could apply. Ask the issuer for the daily calculation.
Q: Does paying the minimum payment avoid interest?
A: Not generally. A minimum payment avoids certain delinquency consequences, but an interest-bearing balance can still accrue interest.
Conclusion
A minimum interest charge on credit card statements usually reflects a disclosed billing rule for small amounts of interest. Check the card agreement, confirm whether interest was actually due, and use a payoff strategy that restores your grace period where available.
Disclaimer: This article is for general information only and is not financial or legal advice. Policies and billing practices vary by issuer and provider. Verify account-specific questions with the company and your credit card issuer.