What is Good Sportsman Charge on Credit Card?

A Good Sportsman charge on credit card statements may come from GSM Outdoors, a company behind several outdoor-product brands. You may know a Stealth Cam or another product name better than the parent company.
Some cellular trail cameras use paid data plans. This guide explains how to match a gear purchase or camera subscription and stop unwanted future billing.
What Is a Good Sportsman Charge on Credit Card?
Good Sportsman Marketing is a company name associated with GSM Outdoors, a seller of outdoor recreation products and related brands. A card entry may show the company name rather than the brand printed on the item.
GSM-related purchases can include outdoor equipment and accessories. Some cellular trail camera products also use recurring data plans that may charge a saved card.
Stealth Cam’s official website explains that data plans can be changed through its Command app. Its support page says a plan change may charge the payment card on file.
The descriptor alone does not establish that every Good Sportsman payment is a trail camera renewal. Match the card amount with a specific order, device, or data plan.
Why You May See Good Sportsman Instead of a Product Brand
You may have purchased outdoor equipment from a company in GSM Outdoors’ portfolio. The brand may appear in your checkout and receipt while the parent business appears on the card.
A cellular trail camera can have a data subscription used to transfer images. A renewal may post even when you have not recently checked the camera, depending on its active plan.
One account can manage more than one camera. Two charges may represent separate devices, plan changes, or another order, so compare all active subscriptions.
A gift purchaser or another authorized user may have placed an order using the card. Ask about recent outdoor equipment spending before reporting an unknown payment.
Legitimate company names can also be used in transactions you never approved. When no matching receipt exists, the issuer should investigate the payment rather than assuming it is safe.
How to Check a Stealth Cam Data Plan
Open the Stealth Cam Command app linked to a camera you own. Review the device list and available data plans, then compare recent plan payments with the statement.
Stealth Cam’s official help says you can select a camera, choose Change under its data plan, select another plan, and save the changes. Check the app version because menu names may vary.
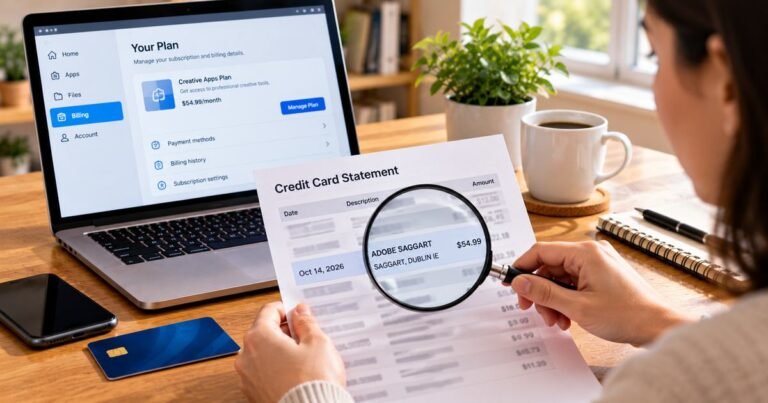
Search your email for GSM Outdoors, Stealth Cam, Command, data plan, order confirmation, and the charge amount. A subscription receipt may identify a camera rather than a retail item.
If you own several devices, inspect every active camera and billing schedule. Closing one device’s plan may not affect another camera with its own data service.
If no camera plan matches, check separate outdoor gear receipts or ask official support to identify the account associated with the amount.
Stop a Camera Plan or Correct a Renewal
Stealth Cam publishes help for suspending a camera, stopping the billing cycle, and removing devices from the app. Use its current instructions for the exact camera and subscription.
Do not assume powering off or discarding a camera stops the billed plan. A billing account can continue until you suspend or cancel it through the service.
Save screenshots of the account’s status and the effective date of any change. Those records matter if another renewal is charged later.
If a plan change triggered an unexpected payment, compare the actual selected plan and date with the official help instructions. Ask support for a transaction explanation.
If you never authorized a camera plan, contact your issuer and the verified provider. Cancellation of an unwanted plan and investigation of an unauthorized charge may both be needed.
Product Returns, Refunds, and Duplicate Entries
A one-time outdoor gear order differs from a data subscription. Check whether the amount reflects a product, plan, shipping fee, or another agreed purchase.
Return policies can vary by product type, seller, and the store where you bought the gear. The manufacturer may not control a purchase you made from an independent retailer.
If a refund is approved, it often posts as a separate credit. Keep its confirmation and monitor the final card statement.
Two entries close together can reflect an authorization and completed purchase. Compare the status of each before assuming the card was charged twice.
If the issuer shows a merchant location or name inconsistent with the account, request the full transaction record. A familiar parent-company label does not prove which product was billed.
How to Verify the Statement Entry
First open the transaction in the secure app provided by your credit card issuer. Copy the exact description, amount, date, and merchant location. Even one extra character can distinguish a merchant from an unrelated company.
Check whether the entry is pending or posted. Pending authorizations can change or disappear during settlement. Our guide to pending credit card charges explains why the final amount may differ. A temporary hold and its final payment may briefly appear together, so confirm whether both amounts actually posted.
Search your email, order history, and downloaded receipts for the exact payment amount. Also check whether a family member or other authorized user recognizes the purchase. A legitimate payment can use a legal business name you never saw at checkout.
Ask the issuer for expanded merchant details if your own records do not help. These may include the legal seller, country, transaction method, and merchant category. The bank may have more information than the shortened name displayed on your statement.
If you see a refund or duplicate-looking charge, compare every posting date and status. A refund normally appears as a separate credit. Two fully posted debits should be matched to two actual receipts or reviewed as a possible billing error.
What to Do If the Payment Was Unauthorized
If nobody approved the transaction, contact the issuer through the number printed on your card or its authenticated app. Report possible unauthorized use promptly. Do not use a phone number from an unsolicited billing text.
Ask whether a card lock, replacement card, or account password change is needed. The bank can guide those steps based on its fraud review. Replacing a card does not always cancel a separate legitimate agreement with a merchant.
The Consumer Financial Protection Bureau explains that many credit card billing errors require a written notice within 60 calendar days after the first statement showing the error was sent. Use the designated billing-error address and keep a copy of the notice.
A disputed transaction is investigated rather than automatically refunded. Preserve receipts, cancellation messages, card alerts, and the issuer’s case number. You may still need to pay the undisputed portion of your account while the investigation continues.
Do not email your entire card number, CVV, or one-time banking password to a stranger who claims to identify a charge. Verified payment support can generally work with limited transaction information.
Make Future Card Charges Easier to Recognize
Enable transaction notifications if your issuer supports them. An alert received near checkout can help you connect a later statement description to the actual purchase.
Save digital invoices by merchant and date. Keep the account email, any subscription renewal notice, and the payment confirmation together. Those records can be useful months after the original order.
If you find a legitimate recurring agreement that you no longer want, cancel using the merchant’s verified process. Deleting an app or replacing a card does not necessarily terminate the agreement. Save the written cancellation confirmation.
Review your statement each month even when autopay is active. A small unexpected transaction deserves the same careful identity check as a large one, although a small amount alone does not prove card testing or fraud.
Official Sources and Identification Limits
Good Sportsman Marketing is associated with GSM Outdoors brands, which include Stealth Cam and other outdoor equipment. Stealth Cam’s official help confirms paid cellular data plans in its Command app and explains that a plan change can charge the saved card.
You can check Stealth Cam’s official camera data-plan instructions for the documented details discussed above. The CFPB’s official billing-error guide explains how to challenge errors on your card statement.
FAQs On Good Sportsman
Q: Is Good Sportsman connected with GSM Outdoors?
A: The company name is associated with GSM Outdoors and outdoor recreation brands. Match your own product receipt or subscription record.
Q: Could this be a Stealth Cam subscription?
A: Yes. Stealth Cam offers cellular data plans, and its help pages explain plan management through the Command app.
Q: How do I stop the recurring data plan?
A: Use the current Stealth Cam app instructions to suspend or cancel each applicable camera plan, then save confirmation.
Q: What if I have never bought outdoor equipment?
A: Ask other authorized card users and have your issuer investigate an unfamiliar posted charge.
Conclusion
A Good Sportsman charge on credit card statements needs to be matched to your own payment records. Your gear receipt or Command app plan history should identify the payment before you decide whether to cancel or dispute it.
Identify the merchant before requesting a cancellation or refund. If you cannot recognize the payment, ask your credit card issuer to investigate and preserve all supporting records.
Disclaimer: This article is informational only and is not financial or legal advice. Company policies and credit card issuer procedures may vary, so verify your account-specific questions with the business or your bank.