How to Calculate APR Charge on Credit Card? Explained

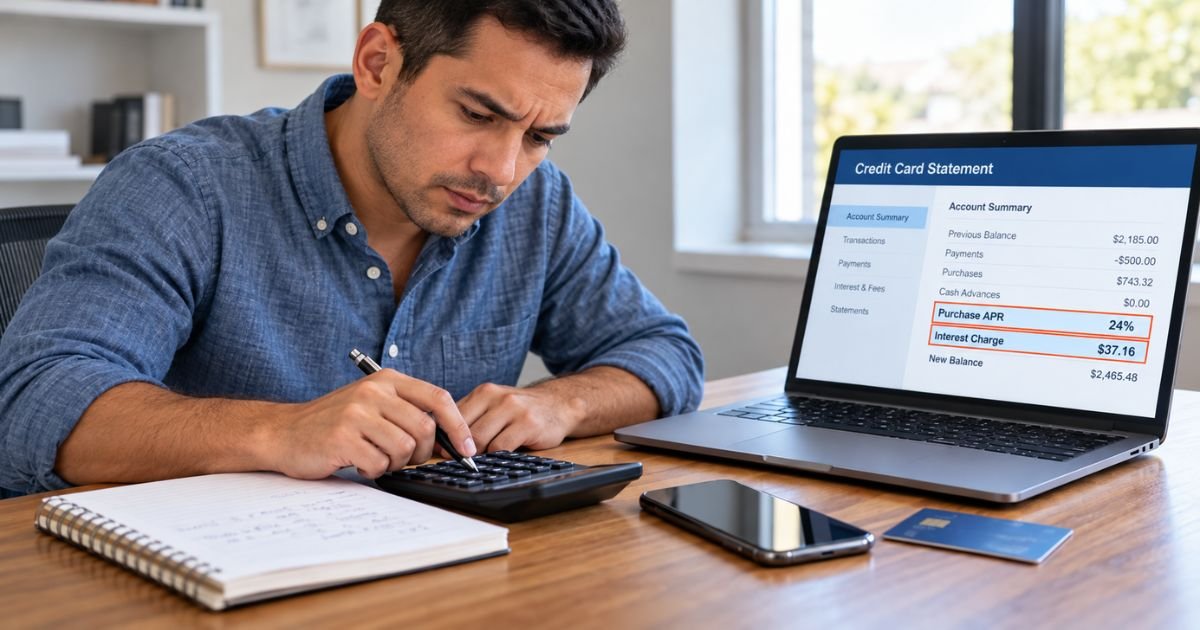
Learning how to calculate APR charge on credit card balances can help you understand why interest appears on your monthly statement. You may notice a purchase interest charge even when you’ve made your minimum payment on time.
The good news is that credit card interest follows a calculation you can estimate yourself. This guide explains the APR formula, shows real examples, and helps you reduce or avoid unnecessary interest.
What Is an APR Charge on Credit Card?
An APR charge on credit card statements generally refers to interest charged when you carry an unpaid balance. APR stands for Annual Percentage Rate, which represents the yearly interest rate applied to eligible credit card balances.
APR itself isn’t a separate fee. Your credit card issuer uses the applicable APR to calculate interest on purchases, cash advances, or balance transfers.
For example, if your card has a 24% purchase APR, you don’t automatically pay 24% of your balance every month.
Instead, your issuer generally converts that annual rate into a daily rate and applies it to your eligible unpaid balance.
You can usually avoid purchase interest by paying your full statement balance by the due date while maintaining your card’s grace period.
How to Calculate APR Charge on Credit Card: Step-by-Step
Most credit card issuers calculate interest using a daily periodic rate and your outstanding balance.
You can estimate your interest charge using this formula:
Interest Charge = Balance × (APR ÷ 365) × Number of Days
This simplified formula assumes your balance stays the same throughout the period and doesn’t include daily compounding.
Follow these steps to calculate your estimated interest.
Step 1: Find your credit card APR
Check your latest credit card statement or online account.
Suppose your purchase APR is 24%.
Convert the percentage into a decimal:
24 ÷ 100 = 0.24
Step 2: Calculate your daily interest rate
Divide your APR by 365 days.
0.24 ÷ 365 = 0.00065753
Your daily periodic rate is approximately 0.06575%.
Some issuers use 360 days instead of 365, so check your card agreement.
Step 3: Multiply by your balance
Suppose you carry a $1,000 purchase balance.
$1,000 × 0.00065753 = $0.65753
You’re accumulating approximately 66 cents in interest per day.
Step 4: Multiply by the billing cycle length
Assume your billing cycle lasts 30 days.
$0.65753 × 30 = $19.73
Your estimated purchase interest charge is $19.73.
The actual amount may be slightly higher if your issuer compounds interest daily.
APR Charge Calculation Examples
The following table shows estimated interest charges using a 24% APR and a 30-day billing cycle.
| Credit card balance | APR | Estimated interest |
|---|---|---|
| $500 | 24% | $9.86 |
| $1,000 | 24% | $19.73 |
| $2,000 | 24% | $39.45 |
| $3,000 | 24% | $59.18 |
| $5,000 | 24% | $98.63 |
These calculations assume a constant balance, no grace period, and no interest compounding.
Your actual statement may show a different amount because credit card balances often change throughout the month.
How to Calculate APR Using Average Daily Balance
Many credit card issuers use the average daily balance method to determine interest charges.
This method considers how much you owe each day of your billing cycle.
For example, suppose you have a 24% purchase APR and a 30-day billing cycle.
You carry a $1,000 balance for the first 10 days. Then you make a $500 payment, leaving $500 for the remaining 20 days.
Your calculation would look like this:
| Period | Daily balance | Total balance-days |
|---|---|---|
| First 10 days | $1,000 | $10,000 |
| Next 20 days | $500 | $10,000 |
| Total | $20,000 |
Divide the total balance-days by 30:
$20,000 ÷ 30 = $666.67
Your average daily balance is approximately $666.67.
Now calculate the estimated interest:
$666.67 × (0.24 ÷ 365) × 30 = $13.15
Making the $500 payment reduced your estimated interest from $19.73 to $13.15.
Actual calculations may vary because of compounding, payment posting dates, and other transactions.
Where Can You Find Your Credit Card APR?
You can generally find your APR on your monthly statement, online banking account, or credit card agreement.
Look for a section labeled Interest Charge Calculation, which typically shows your applicable APRs and balances subject to interest.
Your credit card may have several APRs.
| APR type | What it applies to |
|---|---|
| Purchase APR | Regular purchases |
| Cash advance APR | Cash withdrawals or qualifying advances |
| Balance transfer APR | Transferred balances |
| Introductory APR | Eligible transactions during a promotional period |
| Penalty APR | Certain balances after qualifying payment violations |
Always use the APR that applies to the balance you’re calculating.
A balance transfer or cash advance may have a different rate from ordinary purchases.
Why Is Your Actual APR Charge Different?
Your estimated interest may not match the exact amount on your statement.
Several factors can affect the calculation.
Daily compounding
Some issuers add interest to your balance each day. Future interest may then be calculated on the increased balance.
New purchases
Additional purchases may increase your daily balance when those transactions are subject to interest.
Payments during the billing cycle
A payment generally reduces the eligible balance once it posts, potentially lowering future interest.
Different billing cycle lengths
Your billing cycle might contain 28, 30, or 31 days.
Multiple interest rates
Your card may calculate purchase, cash advance, and balance transfer interest separately.
Minimum interest charges
Some credit card agreements allow a minimum interest charge when interest is due.
For an exact explanation, review the interest calculation section of your statement or ask your issuer for a breakdown.
When Does APR Start Charging Interest?
Purchase interest generally depends on whether your credit card has a grace period.
A grace period is the time between the end of your billing cycle and your payment due date.
Most credit cards provide one for eligible purchases.
If you pay your statement balance in full by the due date, you can typically avoid purchase interest.
However, if you carry a balance and lose your grace period, interest may begin accumulating on new purchases from their transaction dates.
Cash advances generally begin accumulating interest immediately and usually don’t receive a purchase-style grace period.
Balance transfers may also have different interest rules.
How to Avoid or Reduce APR Charges
You can reduce credit card interest by managing your balance and payment schedule.
- Pay your statement balance in full. This generally helps you avoid purchase interest when your grace period applies.
- Pay more than the minimum. Larger payments reduce the outstanding balance and future interest.
- Make payments earlier. Paying sooner may lower the daily balance used to calculate interest.
- Consider eligible 0% APR promotions. These may temporarily reduce interest on qualifying transactions.
- Request a lower APR. Your card issuer may consider reducing your rate based on your account history.
- Avoid unnecessary cash advances. They often carry higher APRs and additional transaction fees.
If you’re carrying debt on multiple cards, paying extra toward the highest-interest balance can generally help reduce overall interest costs.
Can You Dispute an Incorrect APR Charge?
Yes. If you believe your credit card issuer calculated interest incorrectly, you can request a billing review.
First, compare your statement balance, APR, payments, and billing dates.
Check whether a promotional rate expired or a previous unpaid balance affected your grace period.
If the charge still seems incorrect, contact your issuer and ask for an explanation.
For qualifying billing errors, federal rules generally require you to send written notice within 60 days after the issuer sent the first statement containing the error to preserve your formal dispute rights.
A legitimate interest charge isn’t automatically refundable simply because you didn’t expect it.
FAQs On How to Calculate APR Charge on Credit Card
Q: How much interest is 24% APR on a $1,000 credit card balance?
A: At 24% APR, a constant $1,000 balance would generate approximately $19.73 in simple interest over 30 days. Your actual charge may differ because of daily compounding, payments, and your card’s billing method.
Q: How do I calculate monthly APR interest on my credit card?
A: Divide your APR by 365, multiply by your eligible balance, and multiply by the number of days in your billing cycle. For changing balances, calculate interest using your average daily balance or daily transactions.
Q: Do I pay APR interest if I pay the minimum payment?
A: Generally, yes. Paying the minimum usually keeps your account current but doesn’t prevent interest on the remaining eligible balance. Paying your required statement balance in full is typically necessary to avoid purchase interest.
Q: Is APR charged every month on a credit card?
A: Not automatically. Your issuer generally charges interest when eligible balances accrue interest during the billing cycle. If you maintain your grace period and pay your full statement balance on time, you can usually avoid purchase interest.
Conclusion
Understanding how to calculate APR charge on credit card balances helps you estimate borrowing costs and understand your monthly statement. The basic method involves dividing your APR by 365 and applying that daily rate to your eligible balance over the billing period.
Your actual interest may vary because of daily compounding, payments, purchases, and different APRs. To reduce charges, pay your balance as early as possible and avoid carrying unpaid purchase balances whenever you can.
Disclaimer: This article is for informational purposes only and does not provide financial or legal advice. APR calculations, compounding methods, grace periods, and billing policies may vary by credit card issuer. Verify account-specific interest charges and calculations directly with your credit card company.