What is TGTG Charge on Credit Card?

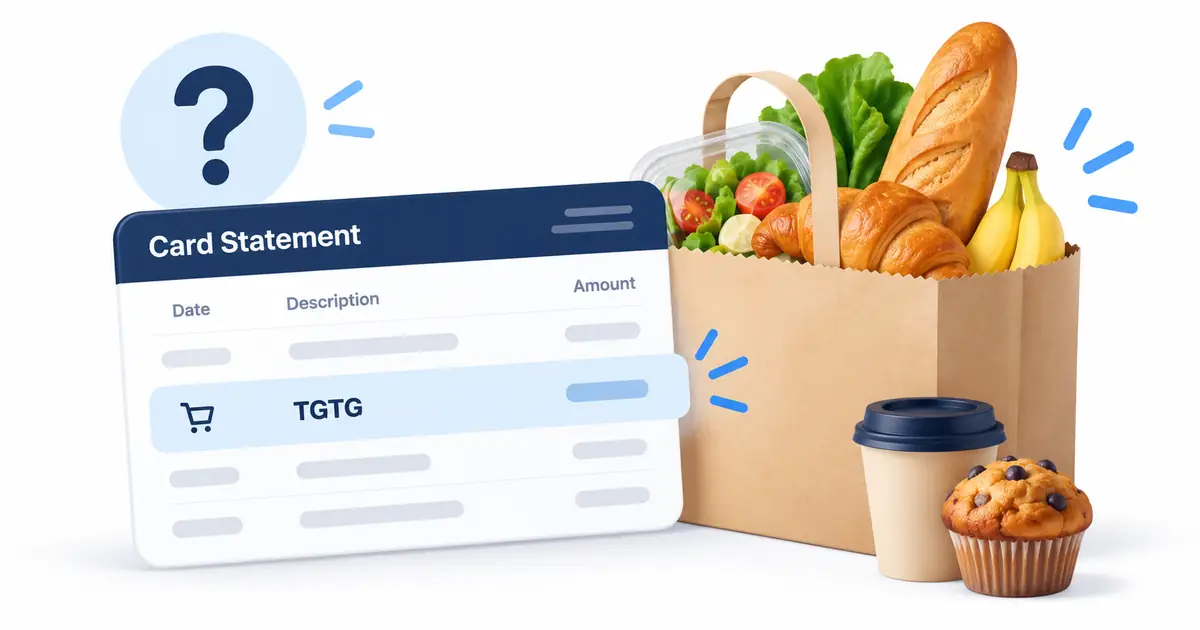
An unfamiliar TGTG charge on credit card entry can feel confusing when you do not recall making the payment. Many statement labels belong to real purchases, but the name alone does not prove you authorized this transaction.
This guide explains what the descriptor may mean, which records help identify it, and how to stop or dispute a payment when appropriate.
What Is a TGTG Charge on Credit Card?
TGTG commonly abbreviates Too Good To Go, a food-saving app where you order surplus food from participating stores. The card statement may show the app’s abbreviation instead of the bakery, café, or grocery shop where you picked up the food.
A billing descriptor is the short merchant name passed through the card payment system. The displayed name may be shortened or may belong to a payment processor instead of the seller you remember. Compare the full statement entry with a real invoice before drawing conclusions.
Why TGTG Might Appear on Your Statement
You ordered a discounted food bag through Too Good To Go. Check the receipt or account activity that would confirm the purchase rather than treating this possibility as certain.
An authorized household member used the app with your saved card. The posted date can fall after the original checkout, so a same-day search may miss a valid match.
An order was placed on a different date from your pickup. An authorized user can explain an unfamiliar transaction without suggesting that your card was stolen.
A pending payment authorization is still showing alongside a later completed charge. If you cannot match the amount and merchant record, ask your issuer to identify who actually received the payment.
How to Verify a TGTG Payment
Open your card app and write down the complete description, amount, currency, and date. Also note whether the item is pending, posted, refunded, or reversed. Those details help you avoid reporting the wrong payment.
Open Too Good To Go and review the order and pickup history. Use the statement amount as your starting point, but allow for a different purchase and posting date.
Match the price, currency, collection location, and order date. Check both the main account and any older email address that could have received the original receipt.
Look for a confirmation email or in-app receipt. Look for the actual invoice number, item, or payment schedule rather than relying on the brand name alone.
Check whether a transaction is pending or permanently posted. Keep a copy of the supporting record if you find a likely match; it will help if you need a correction.
Why the Merchant Name May Look Different
Banks often shorten the text that identifies a payment. Some entries include a website, a payment company, a location, or a transaction reference instead of the storefront name. Your issuer may have more detail than its mobile app displays.
A familiar dollar amount is only a clue. Compare the seller, last four card digits, receipt reference, and date together. If several household members use the card, check authorized purchases privately.
Too Good To Go orders usually involve specific purchases rather than an ordinary monthly subscription. A separate order code on your statement can make a familiar store visit look unfamiliar.
Pending Holds, Double Charges, and Posting Dates
A pending authorization reduces available credit temporarily but may never become a final sale. A completed charge is different because the merchant has submitted it for settlement. Check both entries before assuming you paid twice.
Some merchants first authorize one amount and later post a final amount. Processing delays, exchange rates, or taxes may also change what you see. Ask the merchant or issuer for a transaction breakdown rather than guessing at a fee.
If both entries settle and no receipt explains them, keep screenshots of both transaction details. Ask the merchant whether there was a duplicate submission. Your issuer can explain the dispute process if the merchant cannot fix it.
How to Stop Future TGTG Charges
Determine whether this was a one-time purchase or a recurring arrangement. Similar amounts on different dates can suggest repeat billing, but only the agreement or merchant records can confirm an active subscription.
Do not assume a TGTG transaction is fraudulent because you did not recognize the store name. Also do not assume two entries are both final without checking the pending status.
For a legitimate subscription, cancel through the verified account or company’s support channel and save the confirmation. Removing an app or replacing a card may not end a valid billing agreement. Check the effective cancellation date and any remaining balance.
How to Request a Refund or Correction
When you recognize the company but the amount is wrong, contact the seller with the receipt and transaction date. Explain the exact problem, such as an unwanted renewal, duplicate billing, or missing service. Avoid sending your complete card number by email.
A canceled membership and an approved refund are not the same thing. The seller’s contract, refund policy, and consumer-protection rules determine the options available. Ask for a written response and watch for the actual account credit.
If you paid through an intermediary, ask whether the product seller or the processor handles the request. A processor’s name on the statement does not automatically mean it controls the product or cancellation. Keep the invoice reference and all support messages.
What to Do if You Never Authorized the Charge
If no receipt or authorized card user explains the payment, contact the credit-card issuer promptly. Use the phone number on the card or the bank’s own app. Ask about protecting the account and disputing the transaction.
Review other recent activity for unfamiliar small payments and repeated billing. Change passwords on affected services and enable transaction alerts if possible. Do not give anyone a banking verification code to investigate a mystery charge.
For many qualifying U.S. credit-card billing errors, written notice should reach the issuer within 60 days after it sent the first statement showing the error. A call is useful, but written notice may be needed to protect your rights. Keep paying amounts you do not dispute.
Helpful Related Guides and Official Support
To compare other statement labels and next steps, read other food and self-service charges, contesting an incorrect payment. These topics may look similar but do not necessarily involve the same merchant or the same payment agreement.
For account-specific guidance, consult Too Good To Go’s website. Use official support pages directly rather than entering sensitive card information on a search-result website. Review any instructions for your particular account and location.
FAQs On TGTG Charge on Credit Card
Q: Is a TGTG charge always fraudulent?
A: No. TGTG can be associated with a legitimate purchase or account entry, but the descriptor alone cannot prove authorization. Check your own receipt and ask the issuer for merchant details if needed.
Q: Can a TGTG transaction repeat?
A: It depends on the seller’s arrangement and the service you used. Check transaction dates, order history, and any active membership or payment schedule before assuming a subscription.
Q: How can I identify the exact TGTG payment?
A: Compare the full description, amount, date, receipt, and linked account. If none matches, use the verified company’s support channel or your issuer’s merchant-identification help.
Q: What if I do not recognize or approve the charge?
A: Report it promptly to your card issuer through an official contact method. Ask about a dispute and account protection, then save the case number and later statements.
Conclusion
A TGTG charge on credit card is easier to understand when you compare the full descriptor with a real order, invoice, or account record. Do not assume the name alone identifies the exact item or proves fraud.
If you cannot explain the transaction or believe it was unauthorized, act promptly through verified support or your card issuer. Save the outcome and monitor your next statement.
Disclaimer: This article is for general information, not financial or legal advice. Policies and deadlines may vary by issuer and country. Verify account-specific questions with the merchant or your bank.