Do You Charge Tax on Credit Card Fees?

If you are asking do you charge tax on credit card fees, the answer depends on which fee you mean and which state governs the sale. A processing company charging your business is not identical to a card surcharge you collect from a customer.
Here is how to check the right rules and understand the amount before you pay, accept, or challenge a card transaction.
Tax on Credit Card Fees: What It Means for Card Payments
A processor fee is the cost a payment provider charges a business for accepting card payments. A credit card surcharge is an extra amount a business may try to add to the customer’s bill for paying by card. The tax treatment of a surcharge can depend on whether it is part of a taxable sale.
California’s tax agency has stated that a separately charged percentage reimbursement for processing a taxable merchandise sale can be part of taxable gross receipts. That is a jurisdiction-specific example, not a rule that applies unchanged in every state.
Processing cost paid by the merchant
Your card processor might deduct a percentage and fixed fee before depositing sales proceeds. This is generally an operating cost rather than an extra amount the customer paid directly to you. You should record gross sales and the processor expense separately.
If you want to know whether your processor must charge tax on its own service to you, review the invoice and applicable state treatment of those services. The taxability of processing services is a different question from whether a customer surcharge enters the sales tax base.
Surcharge passed directly to a customer
Suppose you sell an item for $100 and add a separate $3 fee because the buyer uses a credit card. Depending on state law, that $3 may be treated as part of the sales price when the underlying sale is taxable. California specifically recognizes this principle in its published sales-tax annotations.
Do not assume that calling the $3 a handling charge removes it from taxable receipts. Tax authorities often look at what the payment represents rather than the label alone. You must also confirm whether that surcharge is permitted under applicable card-network and state requirements.
The difference between convenience fees and surcharges
A convenience fee can relate to an alternative payment channel or a particular service arrangement. A card surcharge is usually tied to the customer choosing credit rather than another payment method. These categories can have different restrictions and tax consequences.
Review your acquirer’s policies instead of copying a competitor’s checkout language. Do not automatically charge both fees. A flat fee is not necessarily exempt from sales tax simply because it is not calculated as a percentage.
Calculate the tax base using local law
Where a state treats a surcharge as taxable consideration, calculate sales tax on the taxable sale plus the qualifying surcharge. For a hypothetical $100 taxable item, a $3 taxable surcharge, and an assumed 8% rate, the illustrative tax would be $8.24 on a $103 tax base.
Other jurisdictions can define taxable receipts differently, and exempt items introduce additional questions. Do not use the example as universal tax software logic. Ask your state revenue agency for guidance on the precise fee and transaction you offer.
Sales to exempt customers
Tax-exempt sales can require valid exemption documentation and special treatment. A business should not automatically apply a tax rule meant for a taxable retail sale to all transactions. The fee’s treatment may also follow the underlying transaction in ways that require closer analysis.
Ask your tax adviser how to document qualifying exemptions. Keep customer exemption certificates where required and use correct point-of-sale settings. Avoid adjusting tax totals manually without a clear legal basis.
What a customer should do about an unexpected fee
Check whether the merchant disclosed the surcharge before payment and whether the tax was calculated on the correct base. Request an itemized receipt showing subtotal, fee, tax rate, and final total. A customer might be seeing a legitimate, taxable fee or a billing error.
If the merchant cannot explain the charge, ask for correction. When the amount remains disputed, the card issuer can explain its billing-error procedure. Do not confuse disagreement with a properly disclosed charge and an unauthorized card transaction.
Identify the exact type of fee or transaction
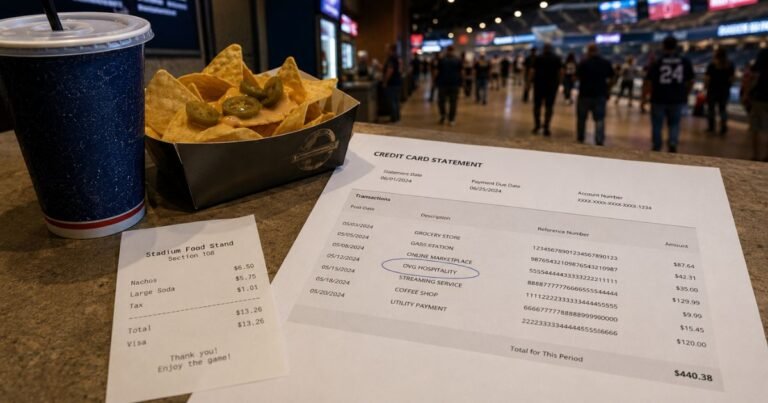
A credit card statement or merchant processing report can contain several kinds of charges that sound similar. A purchase amount, processing fee, surcharge, convenience fee, interest charge, and tax are different items with different rules. Start by recording who charged whom, what was sold, and how the transaction was described.
Review the underlying invoice, payment receipt, and service agreement before interpreting the number. A processor fee taken from a merchant payout is not automatically the same as an additional amount collected from a consumer. If you cannot tell which item you have, ask the payment provider to supply an itemized explanation.
Review your payment provider agreement
The card processor or bank agreement usually explains supported transaction methods, settlement timing, fees, refunds, and restrictions. Some payment platforms also have specific rules for high-risk products, phone-entered payments, and charges added at checkout. Read the version that applies to your business and sales channel.
Do not assume that one provider’s feature is available on every card or device. Check eligibility, acceptable use terms, and your state’s rules before changing how you charge customers. An advertised feature is useful only if your actual account has been approved to use it.
Keep an itemized receipt and consistent records
A useful receipt shows the original price, any permitted extra fee, applicable tax, and total paid. It also records the transaction date and business identity. Itemized records help customers identify legitimate payments and make refunds or corrections easier to investigate.
Keep the invoice, payment-processor reference, refund records, and any customer-approved tip or fee. Separate business expenses from personal costs in your bookkeeping. Your accountant can then reconcile deposits after processor deductions without mistaking net payouts for total sales.
Avoid accidental double-charging
When a payment screen times out, do not immediately submit the same charge again. Check the processor dashboard for an authorization or completed transaction first. Two successful payments may create a billing complaint even when the second was unintentional.
If the first transaction is only a temporary hold, it may disappear without a refund being issued. If two charges actually settle, use the processor’s documented void or refund tools as appropriate. Keep the customer informed and retain the transaction identifiers.
Understand authorization and settlement
Authorization is a request for an issuer to approve a possible charge against available credit. Settlement is the later process that finalizes the transaction for collection. They can appear differently in a cardholder’s app, particularly for adjusted amounts or delayed capture.
Do not promise that a pending hold will disappear at a particular hour, because release timing depends on the processor and issuer. Likewise, a processor showing a successful authorization does not always mean the business has received final funds. Reconcile completed settlements and deposits.
Build clear customer-facing disclosure
Customers should be able to understand what they are buying and the total amount before they consent to payment. Unexpected fees or poorly explained tax lines can cause complaints, payment disputes, and lost confidence. Show material charges clearly during checkout rather than adding them afterward.
If a charge depends on the method of payment, identify it plainly and explain any permitted alternative. Obtain consent when the payment platform or law requires it. Do not mislabel a surcharge as government tax or describe a tax as a service fee to make it seem optional.
Official sources and further reading
California CDTFA: Card surcharge sales tax; California CDTFA: Surcharge treatment; IRS: Business expense records. Use official issuer, processor, and revenue agency materials for current account-specific rules.
FAQs On Tax on Credit Card Fees
Q: Is tax charged on the card processor’s fee?
A: The provider’s service-tax treatment depends on local rules and contract terms; it differs from tax on a retail surcharge.
Q: Does California tax a card surcharge on taxable merchandise?
A: California guidance treats certain retail card surcharges as part of taxable gross receipts. Confirm current local rules and exceptions.
Q: Can a business add a card surcharge anywhere?
A: No universal permission exists. Review state law and your card-network or acquirer rules.
Q: Should customers pay sales tax on the fee itself?
A: Possibly, when the fee is part of the taxable sale under applicable state law. Check an itemized receipt.
Conclusion
Whether you charge tax on credit card fees depends on the fee’s legal role and the sale’s jurisdiction. Separate processor expenses from customer surcharges, verify card rules, and apply sales tax only according to applicable law.
Disclaimer: This article is for general information only and is not financial, tax, or legal advice. Issuer and merchant policies and state rules vary. Confirm account-specific questions with your company, tax adviser, or bank.